The widening spread between 30-year and 2-year US Treasury yields: what signals does this term premium send?
2026-10-07 21:22:18
On Wednesday, October 7th, the sovereign bond market experienced synchronized selling pressure again. The yield on 30-year US Treasury bonds rose to approximately 5.72% and the yield on 10-year bonds to approximately 5.34%, both near their highest levels since 2002. The yield on 10-year French government bonds rose to approximately 4.91%, and the yield on 10-year UK bonds to approximately 5.48%. Brent crude oil rose back above $100, and the euro fell below 1.12 against the dollar. The core of the current market discussion has shifted from simply discussing central bank policy to the repricing of long-term interest rates driven by energy inflation, fiscal financing, and term premiums. 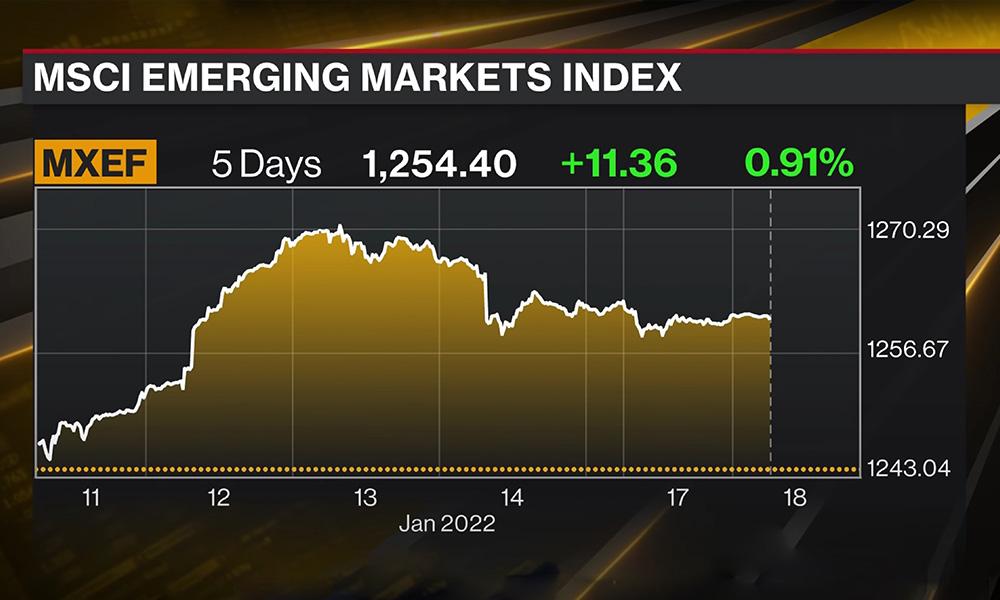
Repricing of Long-Term US Treasuries: Term Premium Becomes the Core Variable
The current pressure on the bond market cannot be simply attributed to the Federal Reserve's policy rates. The 2-year Treasury yield is approximately 4.81%, and the 30-year yield is approximately 5.71%, with a spread of nearly 90 basis points, indicating a clear weakening and steepening of the long-term yield curve. In September, the Fed raised the target range for the federal funds rate by 25 basis points to 3.75%-4.00%, but long-term yields remain significantly higher than short-term yields, suggesting that fiscal financing supply, inflation uncertainty, and investors' demand for term compensation are dominating pricing. This structure differs significantly from traditional policy rate-driven factors. Short-term yields reflect expectations from several future policy meetings, while 30-year bonds need to absorb decades of inflation, debt supply, and fiscal credibility risks. When the market demands a higher term premium, long-term financing costs may remain highly volatile even with limited changes in short-term rates. For stock valuations, housing finance, and highly leveraged companies, it is this long-term funding cost, rather than a single policy meeting, that has a lasting impact.Oil prices have once again become an amplifier of inflation risk.
Brent crude oil rose to around $101.80 during the session, with energy prices further reinforcing inflation stickiness. The latest official data shows that the US Consumer Price Index (CPI) rose 3.4% year-on-year in August, with the energy component rising 16.3% and the core CPI rising 2.4%. This means that even with relatively moderate core inflation, energy shocks can still affect long-term interest rates through transportation, production costs, and residents' inflation expectations. The bond market is currently not focused on single-day oil price changes, but rather on whether the duration of high energy costs is sufficient to alter the medium- to long-term inflation distribution. If energy costs remain high for an extended period, corporate profit margins, residents' actual purchasing power, and the pressure on fiscal subsidies will all be affected, leading long-term bondholders to demand higher inflation compensation. In other words, crude oil is no longer just a commodity market variable, but a crucial macroeconomic pricing factor connecting inflation expectations, central bank policies, and long-term yields.French risk spillover: European bond market begins to be re-stratified according to fiscal quality
The yield on French 10-year government bonds rose to around 4.91% intraday, and the Franco-German 10-year yield spread recently approached 160 basis points, indicating that the market is reassessing fiscal credibility. The yield on UK 10-year government bonds also rose to around 5.48%, near multi-year highs. The key point here is not simply a synchronized weakening of European government bonds, but rather a significant divergence in budget execution capabilities, debt levels, and refinancing pressures among different economies. The most noteworthy aspect of fiscal risk is its feedback mechanism. Rising yields increase the financing costs of new and maturing debt, while increased interest payments compress fiscal space, potentially leading to further increases in risk premiums in the market. Therefore, the debt ratio itself is not the only variable; budget credibility, average debt maturity, and future financing scale also influence pricing. The simultaneous pressure on the euro also indicates that French risk has moved from a single government bond market to a regional exchange rate risk premium. On October 7th, the euro fell back to around 1.1160 against the US dollar.Frequently Asked Questions
Question 1: Why is the rise in long-term US Treasury yields more noteworthy than that of short-term yields? Answer: Short-term yields primarily reflect the Federal Reserve's policy expectations, while long-term yields also include inflation compensation, fiscal supply, and term premiums. The current significant widening of the 30-year vs. 2-year yield spread indicates that the market is increasing the risk compensation required for holding long-term debt, which directly impacts mortgage lending, corporate financing, and long-term asset valuations. Question 2: Why do rising oil prices rapidly affect the Treasury market? Answer: Energy prices influence transportation, production, and household spending, altering inflation expectations. The US energy component still rose 16.3% year-on-year in August; therefore, when oil prices are high again, the market will reassess the sustainability of inflation and the duration of tight policy environments maintained by major central banks.- Risk Warning and Disclaimer
- The market involves risk, and trading may not be suitable for all investors. This article is for reference only and does not constitute personal investment advice, nor does it take into account certain users’ specific investment objectives, financial situation, or other needs. Any investment decisions made based on this information are at your own risk.