













The US dollar was suddenly sold off as it approached its year-to-date high! US Treasury bonds and oil prices both plummeted, and the CPI may trigger a market rally.
2026-10-09 14:08:19
On Friday (October 9) during Asian trading hours, the US dollar index fell slightly, currently trading near the 102 level, down about 0.1%. The core driver of the dollar's weakness was the pullback in US Treasury yields, which in turn was related to the reduction in oil price gains – after Trump ruled out the possibility of resuming military action against Iran before the midterm elections. 
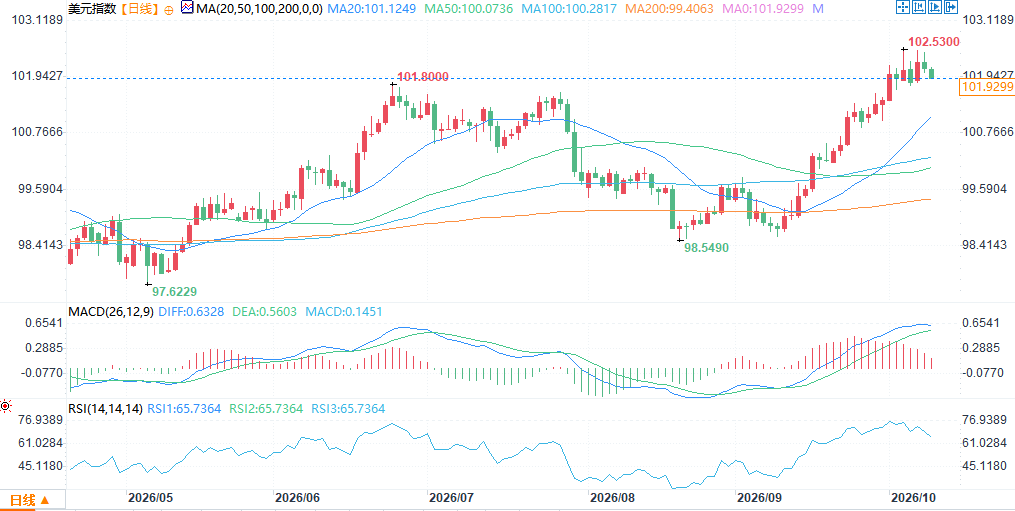 (US Dollar Index Daily Chart, Source: EasyForex) At 14:06 Beijing time, the US Dollar Index was at 102.04.
The US dollar index briefly fell below 102, and the US Treasury yield dropped from 5.35% to 5.23%.
The dollar index extended its decline on Friday as U.S. Treasury yields retreated after failing to sustain their gains. During the Asian session, the dollar index fell as much as 0.2% to below 102, reaching 101.91. The dollar index faced significant selling pressure late Thursday after failing to break through the yearly high of 102.53 reached earlier this year. The 10-year Treasury yield has retreated from Thursday's high of 5.35% to around 5.23%. This pullback indicates weakening short-term momentum in Treasury yields, diminishing support for the dollar's interest rate advantage.II. Trump confirms no attack on Iran before the midterm elections, oil prices pare gains.
U.S. Treasury yields came under pressure as oil prices pared gains after Trump ruled out concerns about a renewed military operation against Iran before the midterm elections. Trump posted on social media, "We will not attack Iran at any time before the November 3rd U.S. midterm elections," adding, "We are having productive discussions with the Islamic Republic of Iran." This statement eased market concerns about an immediate escalation of tensions in the Middle East, causing oil prices to fall, which in turn reduced inflationary pressures and lowered the upward momentum of U.S. Treasury yields. For the dollar, the decline in oil prices and the pullback in U.S. Treasury yields combined to exert downward pressure.CPI data will be a key trigger next week; the market has already priced in at least one interest rate hike this year.
Looking ahead, the main trigger for the US dollar will be the US September Consumer Price Index (CPI) data released next Wednesday. Inflation is expected to have a significant impact on the Federal Reserve's interest rate expectations. Currently, the CME FedWatch tool shows that financial markets have priced in at least one more rate hike this year. If the CPI data is stronger than expected, it may strengthen expectations of a rate hike, supporting the dollar; if the data is weaker than expected, it may further weaken the dollar's interest rate support and exacerbate downward pressure on the dollar. Therefore, the CPI data will be a key variable determining the short-term direction of the dollar.Institutional Views
Standard Chartered's Chief Investment Office released its fourth-quarter outlook, believing the US dollar will remain supported in the short term but gradually weaken in the medium to long term. Specifically, it forecasts a US dollar index target of 100.2 over the next three months and a decline to 98 over 12 months. Short-term support comes from the possibility of further tightening by the Federal Reserve (another rate hike before the end of the year, and not ruled out in the first half of 2027) and the resilience of the US economy. In the medium to long term, the impact of oil prices and tariffs will subside, inflationary pressures will ease, and the continued tightening by the ECB and the Bank of Japan will narrow the interest rate differential advantage. Chris Turner, Global Head of Strategy at ING, pointed out that the September FOMC meeting minutes showed that most officials believed another rate hike before the end of the year was appropriate, and the market has fully priced in a 25 basis point rate hike to 4.25% in December, and expects a further 50 basis point tightening in 2027. Although ING believes that the expectation of further tightening next year is too aggressive, the market is unlikely to challenge this hawkish pricing in the short term. High US Treasury yields and rising volatility have drawn funds away from carry trades, especially impacting Latin American currencies, while the situation in Europe is also providing support for the US dollar. Against this backdrop, the US dollar has received strong support and attracted more funds, with ING expecting the US dollar index to slowly rise to its target of 102.85. The DXY is currently near its yearly high, and short-term upward momentum remains, but the medium- to long-term outlook depends on the evolution of inflation and policy paths.Summarize
The US dollar index weakened further on Friday to around 101.91 due to a pullback in US Treasury yields, with the 10-year Treasury yield falling from 5.35% to 5.23%. Trump's confirmation that there would be no attack on Iran before the midterm elections and the parity rate cuts in oil prices eased inflationary pressures and upward momentum in yields. The market is focused on Wednesday's US September CPI data, which will have a significant impact on the Federal Reserve's interest rate expectations. The market has already priced in at least one rate hike this year. If the CPI is stronger than expected, the dollar may find support; if it is weaker than expected, the dollar may face further pressure. Going forward, attention should be paid to the CPI data, the trend of US Treasury yields, changes in oil prices, and the evolution of the situation in the Middle East. Against the backdrop of a pullback in US Treasury yields and lower oil prices, the dollar faces short-term corrective pressure, but the CPI data may be a key trigger for its directional move. (US Dollar Index Daily Chart, Source: EasyForex) At 14:06 Beijing time, the US Dollar Index was at 102.04.
- Risk Warning and Disclaimer
- The market involves risk, and trading may not be suitable for all investors. This article is for reference only and does not constitute personal investment advice, nor does it take into account certain users’ specific investment objectives, financial situation, or other needs. Any investment decisions made based on this information are at your own risk.

