The pound fell slightly against the yen in Asian trading, with the interest rate differential and policy expectations putting pressure on the pound as it fluctuated at lower levels.
2026-10-13 16:08:19
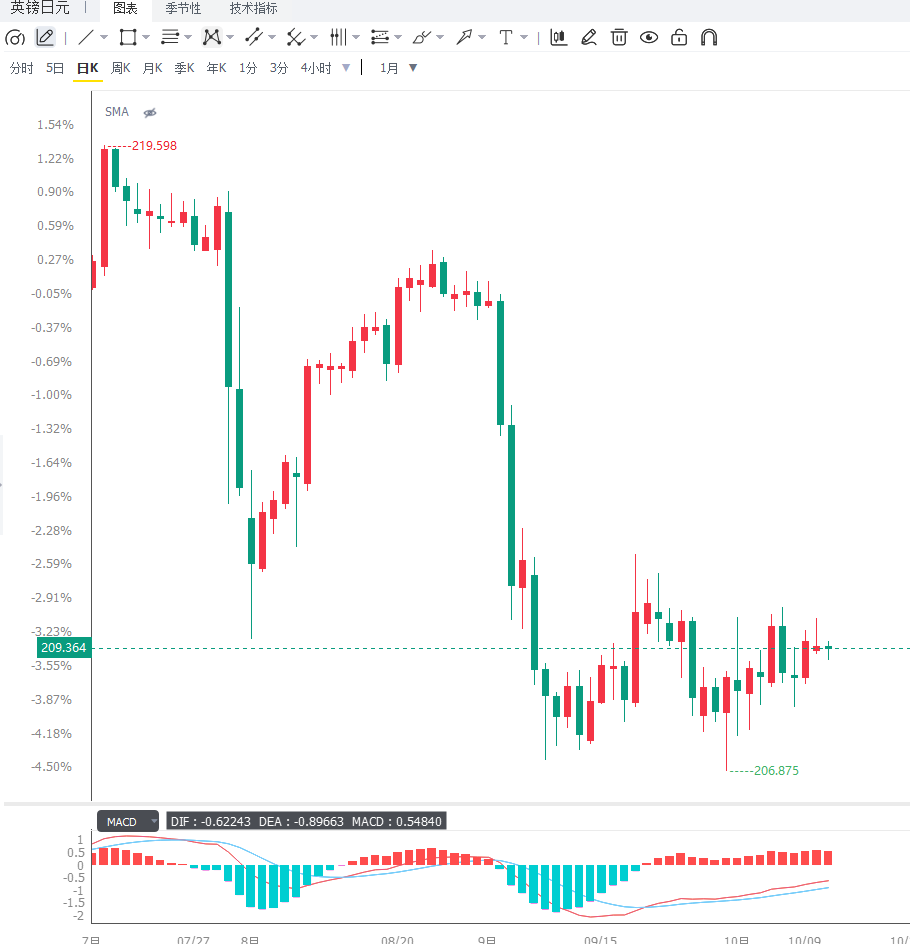
The British pound traded around 209.60 against the Japanese yen in the previous New York close, and then slightly retreated to a range of 209.25 to 209.31 in Asian trading. Looking at the breakdown, the pound closed at approximately 1.3208 against the US dollar and approximately 158.61 against the Japanese yen in the previous trading day, with cross-currency pairs roughly corresponding to a range of 209.5 to 209.6. The US dollar fell back to around 158.25 against the Japanese yen in Asian trading, with the yen strengthening in the short term, putting downward pressure on the pound against the yen.  The pound's support primarily stems from hawkish statements within the Bank of England and its resilience in growth. Monetary Policy Committee member Green recently called for an interest rate hike, arguing that the current 3.75% rate may be insufficient to curb inflation and expressing concern that rising energy prices could create a second round of inflation through wages and pricing behavior. The UK's current inflation rate is 3.1%, and driven by rising energy prices, the market expects it to approach 4% in the coming months. The IMF's latest forecast for UK GDP growth in 2026 has been revised upward to 1.3%, a 0.5 percentage point increase from April, mainly driven by AI-related investment and exports. Based on this, Commerzbank has raised its probability of a Bank of England rate hike in November to "over 50%" and predicts a possible 25 basis point hike in February, potentially bringing the final rate to 4.25%. S&P has also affirmed the UK's sovereign rating at AA/A-1+ with a stable outlook and expects a 25 basis point rate hike by the end of 2026. However, the pound's upward movement is not without constraints. Rising energy prices are squeezing UK import costs and household real income, with the market generally expecting August GDP to contract by 0.1% month-on-month, a significant slowdown from July's 0.4% growth. If Thursday's data confirms a slowdown in growth momentum, market pricing in continued Bank of England rate hikes may be partially revised, and the pound's short-term support will be tested. The logic for the yen is more inclined towards "moderate tightening + safe-haven support." Japan's corporate price index rose 6.8% year-on-year in September, lower than the expected 7.6%, but the yen-denominated import price index surged 24.5% year-on-year, indicating that external cost pressures remain. Bank of Japan Governor Kazuo Ueda has recently emphasized the importance of stabilizing inflation around 2% and leaving room for further rate hikes. The market is currently pricing in a low probability of a second rate hike in October, with an overnight index swap implied probability of about 12%, but the probability of a December rate hike has risen to about 90%. Former Bank of Japan Executive Director Momma believes that the probability of an October rate hike remains 20% to 30%, and the terminal interest rate may rise to about 2% by the middle of next year. As the USD/JPY pair approaches the 159.50-160.00 range, Japanese authorities' intervention could indirectly support the yen. Technically, the GBP/JPY pair remains below recent highs on the daily chart, currently in a consolidation phase after a pullback. Initial resistance is in the 209.80-210.00 range; a break above this level could lead to further resistance at 210.50-210.80, with stronger resistance at 211.20-211.50. Initial support is at the psychological level of 209.00; a break below this level could test 208.50-208.20, with stronger support at 207.80-207.50. If the RSI remains around 50, it indicates a continued tug-of-war between bulls and bears; a break below 50 accompanied by weakening MACD momentum could amplify downward pressure.
 Editor's Summary: The GBP/JPY pair is currently caught in a crossfire between expectations of a Bank of England rate hike supporting the pound and expectations of a Bank of Japan tightening, coupled with safe-haven buying supporting the yen. The resilience of the UK economy, improved AI investment, and sticky inflation provide the pound with an interest rate premium, but rising energy costs and a potential contraction in August GDP limit its upside potential. While the yen is under short-term pressure due to a decline in September PPI, high import costs, high expectations of a December rate hike, and asymmetric risks near the intervention warning line keep it relatively strong. Short-term direction depends on whether UK August GDP exceeds expectations, the impact of US CPI/PPI on the dollar's path, and whether statements from Bank of Japan officials before the October meeting reinforce expectations of an earlier rate hike. Until the 209.00 support level is effectively broken, the overall outlook remains range-bound.
The pound's support primarily stems from hawkish statements within the Bank of England and its resilience in growth. Monetary Policy Committee member Green recently called for an interest rate hike, arguing that the current 3.75% rate may be insufficient to curb inflation and expressing concern that rising energy prices could create a second round of inflation through wages and pricing behavior. The UK's current inflation rate is 3.1%, and driven by rising energy prices, the market expects it to approach 4% in the coming months. The IMF's latest forecast for UK GDP growth in 2026 has been revised upward to 1.3%, a 0.5 percentage point increase from April, mainly driven by AI-related investment and exports. Based on this, Commerzbank has raised its probability of a Bank of England rate hike in November to "over 50%" and predicts a possible 25 basis point hike in February, potentially bringing the final rate to 4.25%. S&P has also affirmed the UK's sovereign rating at AA/A-1+ with a stable outlook and expects a 25 basis point rate hike by the end of 2026. However, the pound's upward movement is not without constraints. Rising energy prices are squeezing UK import costs and household real income, with the market generally expecting August GDP to contract by 0.1% month-on-month, a significant slowdown from July's 0.4% growth. If Thursday's data confirms a slowdown in growth momentum, market pricing in continued Bank of England rate hikes may be partially revised, and the pound's short-term support will be tested. The logic for the yen is more inclined towards "moderate tightening + safe-haven support." Japan's corporate price index rose 6.8% year-on-year in September, lower than the expected 7.6%, but the yen-denominated import price index surged 24.5% year-on-year, indicating that external cost pressures remain. Bank of Japan Governor Kazuo Ueda has recently emphasized the importance of stabilizing inflation around 2% and leaving room for further rate hikes. The market is currently pricing in a low probability of a second rate hike in October, with an overnight index swap implied probability of about 12%, but the probability of a December rate hike has risen to about 90%. Former Bank of Japan Executive Director Momma believes that the probability of an October rate hike remains 20% to 30%, and the terminal interest rate may rise to about 2% by the middle of next year. As the USD/JPY pair approaches the 159.50-160.00 range, Japanese authorities' intervention could indirectly support the yen. Technically, the GBP/JPY pair remains below recent highs on the daily chart, currently in a consolidation phase after a pullback. Initial resistance is in the 209.80-210.00 range; a break above this level could lead to further resistance at 210.50-210.80, with stronger resistance at 211.20-211.50. Initial support is at the psychological level of 209.00; a break below this level could test 208.50-208.20, with stronger support at 207.80-207.50. If the RSI remains around 50, it indicates a continued tug-of-war between bulls and bears; a break below 50 accompanied by weakening MACD momentum could amplify downward pressure. Editor's Summary: The GBP/JPY pair is currently caught in a crossfire between expectations of a Bank of England rate hike supporting the pound and expectations of a Bank of Japan tightening, coupled with safe-haven buying supporting the yen. The resilience of the UK economy, improved AI investment, and sticky inflation provide the pound with an interest rate premium, but rising energy costs and a potential contraction in August GDP limit its upside potential. While the yen is under short-term pressure due to a decline in September PPI, high import costs, high expectations of a December rate hike, and asymmetric risks near the intervention warning line keep it relatively strong. Short-term direction depends on whether UK August GDP exceeds expectations, the impact of US CPI/PPI on the dollar's path, and whether statements from Bank of Japan officials before the October meeting reinforce expectations of an earlier rate hike. Until the 209.00 support level is effectively broken, the overall outlook remains range-bound.
- Risk Warning and Disclaimer
- The market involves risk, and trading may not be suitable for all investors. This article is for reference only and does not constitute personal investment advice, nor does it take into account certain users’ specific investment objectives, financial situation, or other needs. Any investment decisions made based on this information are at your own risk.