High US Treasury yields pressured gold prices, causing gold to fall back to the lower end of its trading range.
2026-10-21 10:14:20
On Wednesday morning in Asia, spot gold continued its downward trend, trading around $4,120 per ounce, further lower than the close of the previous trading day. The core contradiction in gold prices currently lies in the offsetting relationship between safe-haven demand stemming from geopolitical conflicts and inflation and high interest rate expectations triggered by high oil prices. This causes precious metals to oscillate between their "inflation-hedging properties" and "opportunity cost pressures," exhibiting a typical characteristic of being prone to declines and difficult to rises.  Geopolitical risks on the supply side continue to accumulate. On Monday, the Iranian military explicitly stated that Tehran had not completely closed the Strait of Hormuz, but retained the capability to extend the blockade to the Bab el-Mandeb Strait and the Suez Canal. This statement broadened the potential disruption risk from a single chokepoint to the entire Eurasian energy and shipping corridor, escalating market concerns about future logistics chains. On the same day, the Houthi rebels claimed responsibility for attacks on King Khalid International Airport in Riyadh, Saudi Arabia, Saudi Aramco facilities along the Red Sea coast, the Shaybai oil field, and Saudi naval forces. The confluence of multiple conflicts has kept the uncertainty of energy transportation in the Persian Gulf high. This high oil price directly pushes up US inflation figures through the cost channel, reinforcing the Federal Reserve's rationale for maintaining high interest rates, ultimately translating into an opportunity cost of holding gold. This is the fundamental reason why gold prices have weakened despite geopolitical tensions—when inflation is driven by supply shocks, gold's anti-inflation narrative is often suppressed by tightening expectations. At the monetary policy level, market pricing is undergoing a subtle shift. Traders are currently pricing in a 25 basis point rate hike at the Fed's October 27-28 meeting at nearly 16.1%, a significantly higher probability than when Warsh's remarks last week were interpreted as a pause. Although inflation remains above the Fed's 2% target, investors' focus has shifted to whether policymakers will resume tightening later this year after this month's pause. Gold, as a traditional inflation hedge, does not generate interest. When the central interest rate is raised and maintained for a longer period, its attractiveness relative to interest-bearing assets such as bonds systematically decreases. This cross-asset correlation indicates that the weakening of gold prices is not an isolated phenomenon, but rather the result of a combination of a stronger dollar, rising US Treasury yields, and a recovery in risk appetite. From a policy communication perspective, Fed Chairman Warsh's recent speeches scored 5.6/10, slightly below the historical average of 6.1/10, indicating that his communication style is more moderate than usual, but the overall tone remains constructive. He acknowledged that he was "deeply traumatized by the global financial crisis," highlighting a cautious stance while emphasizing structural growth and a surge in investment driven by "good policies." He also declined to predict the outcomes of the October and December meetings, viewing artificial intelligence as a demand-side variable and planning to accumulate new analytical capabilities through on-site hearings and special working groups. More significantly, the Fed's sentiment index remained unchanged at a high of 127.51, well above the neutral benchmark. This means that despite the lack of incremental signals in his speech, the overall policy narrative remains firmly hawkish. For gold, this presents a combination of "short-term lack of dovish catalysts and unresolved medium-term interest rate pressures": as long as the index remains above 127 and the year-end tightening path is not disproven, any rebound in gold prices is more likely to encounter profit-taking resistance. From a global market perspective, the current fluctuations in gold prices are essentially a tug-of-war between geopolitical premiums and the interest rate path. On the one hand, the disruption of Middle Eastern shipping and political turmoil in France (widening the Franco-German interest rate differential to approximately 147 basis points) have increased the demand for safe-haven assets, while central bank gold purchases and ETF holdings have provided structural support for gold prices. On the other hand, if oil prices continue to rise, they will further push up global inflation through cost channels, forcing central banks to extend the high-interest-rate cycle, which in turn will negatively impact precious metal valuations through real interest rates. Furthermore, rising energy costs leading to increased freight and insurance expenses will exacerbate global trade concerns, indirectly suppressing risk assets. This environment is initially favorable for gold, but if it evolves into a stagflationary pattern of slowing growth and high interest rates, the pricing logic of gold will face a more complex test. Therefore, it is inappropriate to simply equate geopolitical tensions with a bullish outlook for gold; instead, attention should be paid to the actual direction of real interest rates and the US dollar. On the daily chart, spot gold is trading below the 20-day Bollinger Band middle line and the 100-day simple moving average. Short-term moving averages are in a bearish alignment, and rebounds are consistently suppressed by these resistance levels. The medium-term bearish structure has not yet been repaired. The RSI is around 41, below the 50 neutral line but not yet in oversold territory, indicating that downward momentum is still releasing and there is room for further declines, a typical weak consolidation pattern. The upper resistance levels to watch are the Bollinger Band middle line around $4170, the 100-day moving average around $4235, and the upper Bollinger Band around $4275. These three levels form a wide supply zone; only a decisive break above $4170 on the daily chart can alleviate the current bearish bias. On the downside, the first support level is the lower Bollinger Band around $4065, a key defense level in the near term. A break below this level could open up deeper downside potential, while holding above it could allow gold prices to oscillate within the $4065-$4170 range. On the 4-hour chart, gold prices have slowly moved down along the short-term moving average after falling from around $4150. The MACD histogram is expanding below the zero line, and the fast and slow lines are diverging downwards, indicating that the bears are still in control. Currently, the price is consolidating in a narrow range between $4115 and $4145. If it breaks below $4110 with significant volume, it may seek support at $4085 or even $4065. An upward breakout would require a decline in real interest rates or an escalation of geopolitical tensions.
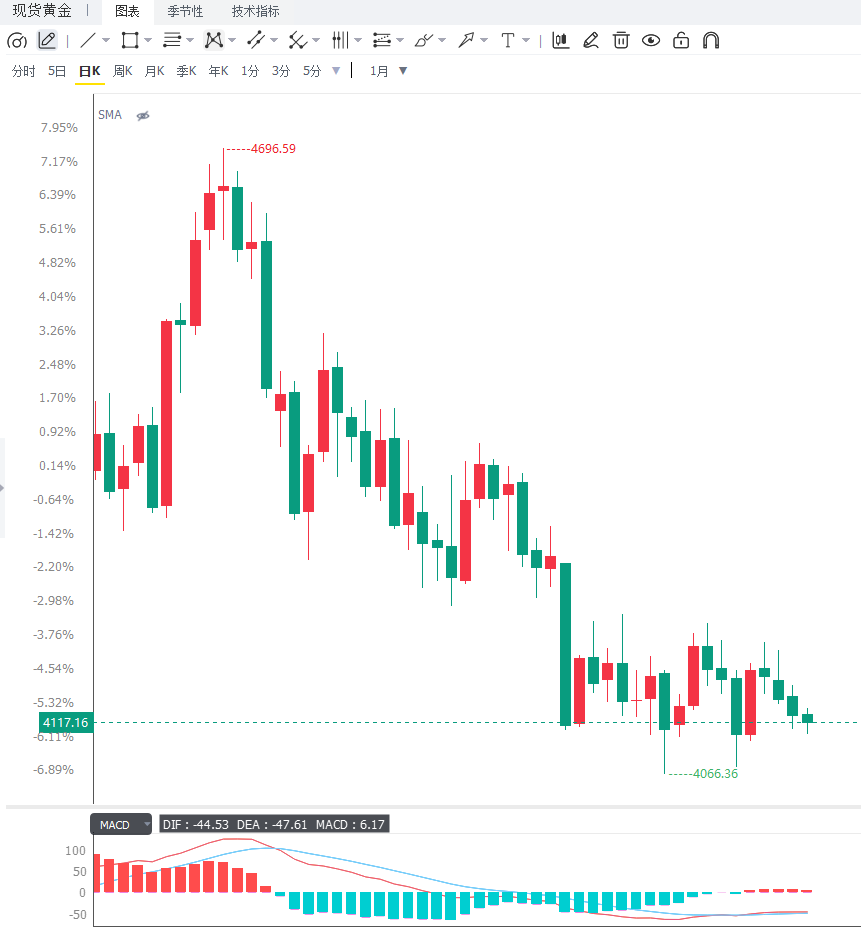 Editor's Summary: The core logic for gold in the short term lies in the support provided by geopolitical risk premiums, while the high-interest-rate environment and strong dollar compress the upside potential. The combined effect of these two factors suggests that gold prices are more likely to fluctuate within the $4065-$4170 range. Three key variables need to be monitored: first, the accessibility of the Strait of Hormuz, the Bab el-Mandeb Strait, and the Suez Canal, which directly determines the duration of the oil price premium and safe-haven sentiment; second, US inflation data and the Fed's year-end policy path. If the probability of an October rate hike continues to rise or expectations of tightening in December strengthen, real interest rate pressures will push gold prices to test the support below $4065; third, the direction of the dollar index. If the dollar weakens again due to reduced yield support, it will provide additional pricing support for gold. In the medium term, before a valid breakout from the current range, gold prices will maintain a weak and volatile pattern. Confirmation of the trend direction still requires the clarification of inflation data and the final path of central bank policy at the end of the year.
Geopolitical risks on the supply side continue to accumulate. On Monday, the Iranian military explicitly stated that Tehran had not completely closed the Strait of Hormuz, but retained the capability to extend the blockade to the Bab el-Mandeb Strait and the Suez Canal. This statement broadened the potential disruption risk from a single chokepoint to the entire Eurasian energy and shipping corridor, escalating market concerns about future logistics chains. On the same day, the Houthi rebels claimed responsibility for attacks on King Khalid International Airport in Riyadh, Saudi Arabia, Saudi Aramco facilities along the Red Sea coast, the Shaybai oil field, and Saudi naval forces. The confluence of multiple conflicts has kept the uncertainty of energy transportation in the Persian Gulf high. This high oil price directly pushes up US inflation figures through the cost channel, reinforcing the Federal Reserve's rationale for maintaining high interest rates, ultimately translating into an opportunity cost of holding gold. This is the fundamental reason why gold prices have weakened despite geopolitical tensions—when inflation is driven by supply shocks, gold's anti-inflation narrative is often suppressed by tightening expectations. At the monetary policy level, market pricing is undergoing a subtle shift. Traders are currently pricing in a 25 basis point rate hike at the Fed's October 27-28 meeting at nearly 16.1%, a significantly higher probability than when Warsh's remarks last week were interpreted as a pause. Although inflation remains above the Fed's 2% target, investors' focus has shifted to whether policymakers will resume tightening later this year after this month's pause. Gold, as a traditional inflation hedge, does not generate interest. When the central interest rate is raised and maintained for a longer period, its attractiveness relative to interest-bearing assets such as bonds systematically decreases. This cross-asset correlation indicates that the weakening of gold prices is not an isolated phenomenon, but rather the result of a combination of a stronger dollar, rising US Treasury yields, and a recovery in risk appetite. From a policy communication perspective, Fed Chairman Warsh's recent speeches scored 5.6/10, slightly below the historical average of 6.1/10, indicating that his communication style is more moderate than usual, but the overall tone remains constructive. He acknowledged that he was "deeply traumatized by the global financial crisis," highlighting a cautious stance while emphasizing structural growth and a surge in investment driven by "good policies." He also declined to predict the outcomes of the October and December meetings, viewing artificial intelligence as a demand-side variable and planning to accumulate new analytical capabilities through on-site hearings and special working groups. More significantly, the Fed's sentiment index remained unchanged at a high of 127.51, well above the neutral benchmark. This means that despite the lack of incremental signals in his speech, the overall policy narrative remains firmly hawkish. For gold, this presents a combination of "short-term lack of dovish catalysts and unresolved medium-term interest rate pressures": as long as the index remains above 127 and the year-end tightening path is not disproven, any rebound in gold prices is more likely to encounter profit-taking resistance. From a global market perspective, the current fluctuations in gold prices are essentially a tug-of-war between geopolitical premiums and the interest rate path. On the one hand, the disruption of Middle Eastern shipping and political turmoil in France (widening the Franco-German interest rate differential to approximately 147 basis points) have increased the demand for safe-haven assets, while central bank gold purchases and ETF holdings have provided structural support for gold prices. On the other hand, if oil prices continue to rise, they will further push up global inflation through cost channels, forcing central banks to extend the high-interest-rate cycle, which in turn will negatively impact precious metal valuations through real interest rates. Furthermore, rising energy costs leading to increased freight and insurance expenses will exacerbate global trade concerns, indirectly suppressing risk assets. This environment is initially favorable for gold, but if it evolves into a stagflationary pattern of slowing growth and high interest rates, the pricing logic of gold will face a more complex test. Therefore, it is inappropriate to simply equate geopolitical tensions with a bullish outlook for gold; instead, attention should be paid to the actual direction of real interest rates and the US dollar. On the daily chart, spot gold is trading below the 20-day Bollinger Band middle line and the 100-day simple moving average. Short-term moving averages are in a bearish alignment, and rebounds are consistently suppressed by these resistance levels. The medium-term bearish structure has not yet been repaired. The RSI is around 41, below the 50 neutral line but not yet in oversold territory, indicating that downward momentum is still releasing and there is room for further declines, a typical weak consolidation pattern. The upper resistance levels to watch are the Bollinger Band middle line around $4170, the 100-day moving average around $4235, and the upper Bollinger Band around $4275. These three levels form a wide supply zone; only a decisive break above $4170 on the daily chart can alleviate the current bearish bias. On the downside, the first support level is the lower Bollinger Band around $4065, a key defense level in the near term. A break below this level could open up deeper downside potential, while holding above it could allow gold prices to oscillate within the $4065-$4170 range. On the 4-hour chart, gold prices have slowly moved down along the short-term moving average after falling from around $4150. The MACD histogram is expanding below the zero line, and the fast and slow lines are diverging downwards, indicating that the bears are still in control. Currently, the price is consolidating in a narrow range between $4115 and $4145. If it breaks below $4110 with significant volume, it may seek support at $4085 or even $4065. An upward breakout would require a decline in real interest rates or an escalation of geopolitical tensions. Editor's Summary: The core logic for gold in the short term lies in the support provided by geopolitical risk premiums, while the high-interest-rate environment and strong dollar compress the upside potential. The combined effect of these two factors suggests that gold prices are more likely to fluctuate within the $4065-$4170 range. Three key variables need to be monitored: first, the accessibility of the Strait of Hormuz, the Bab el-Mandeb Strait, and the Suez Canal, which directly determines the duration of the oil price premium and safe-haven sentiment; second, US inflation data and the Fed's year-end policy path. If the probability of an October rate hike continues to rise or expectations of tightening in December strengthen, real interest rate pressures will push gold prices to test the support below $4065; third, the direction of the dollar index. If the dollar weakens again due to reduced yield support, it will provide additional pricing support for gold. In the medium term, before a valid breakout from the current range, gold prices will maintain a weak and volatile pattern. Confirmation of the trend direction still requires the clarification of inflation data and the final path of central bank policy at the end of the year.
- Risk Warning and Disclaimer
- The market involves risk, and trading may not be suitable for all investors. This article is for reference only and does not constitute personal investment advice, nor does it take into account certain users’ specific investment objectives, financial situation, or other needs. Any investment decisions made based on this information are at your own risk.