Retail sales are weak externally but strong internally! Core retail sales exceeded expectations, and the data did not change expectations of an interest rate hike.
2026-11-17 21:48:30
Retail sales are a core high-frequency indicator for observing US household demand for goods and a crucial basis for the Federal Reserve to assess the domestic demand environment and determine interest rate policy. Retail data is based on nominal statistics and is easily affected by highly volatile categories such as automobiles and gasoline. Market analysis focuses on the core retail sales group, excluding automobiles, gasoline, building materials, and catering. This indicator directly serves the calculation of the consumption component of GDP and has a higher signal value than total retail sales. It also needs to be cross-referenced with inflation data to distinguish between genuine demand expansion and inflated sales figures due to price increases. The October retail data released this time showed a clear divergence. Overall retail sales grew by 0.2% month-on-month, in line with market expectations, and rose to 6.82% year-on-year. Excluding automobiles, retail sales grew by 0.6% month-on-month, higher than the expected 0.4%. Gasoline sales rose by 1.5% month-on-month, a significant slowdown from September's 6.0%. Automobile and auto parts sales declined by 1.6% month-on-month, becoming the main factor dragging down overall retail sales. Excluding automobiles and gasoline, retail sales grew by 0.5% month-on-month, the same as in September. Core retail sales in the control group grew by 0.6% month-on-month, also exceeding market expectations. Coupled with the slightly higher-than-expected 0.4% month-on-month CPI in August, this adds an inflationary dimension to the current consumer profile. 
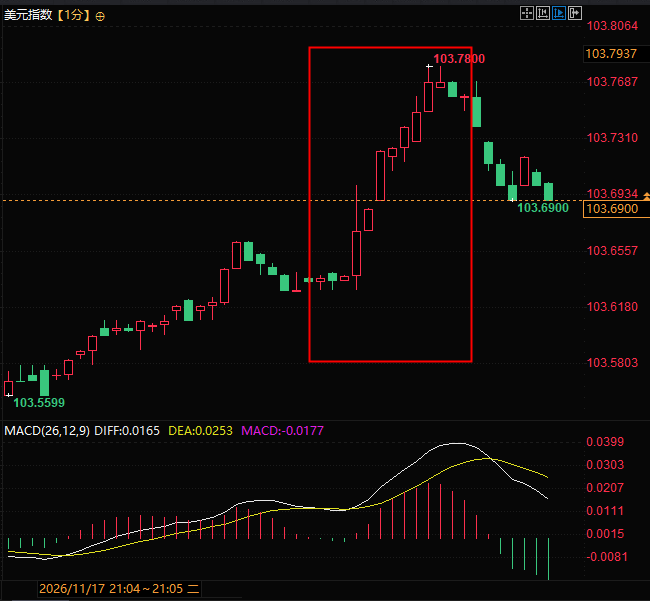 (US Dollar Index 1-minute chart, source: FX678)
Despite the divergence in specific sectors, the resilience of domestic demand is real.
From a traditional analytical framework, the overall weak retail sales figures are merely a symptom; the core resilience lies within the sub-categories. Automobiles, being high-value durable goods, naturally possess high volatility. Their individual weakness dragged down the headline data, but the strength of core retail sales after removing distracting factors indicates that consumer spending on non-automobile and non-energy goods has not cooled. Fourth-quarter consumer spending is supporting the economy better than previously anticipated. With end-user demand remaining resilient, coupled with continued downward pressure on inflation, this retail data does not alter expectations of interest rate hikes. The risks to watch are concentrated in the durable goods sector. Automobiles are among the first major expenditures to be cut when income expectations tighten. It is necessary to observe whether durable goods such as furniture and appliances weaken simultaneously to determine whether the contraction in consumption is a single-category adjustment or a systemic decline in household spending. Furthermore, retail sales are nominal data, and the high year-on-year growth includes price factors. It is also necessary to consider household credit and savings rates to determine whether the underlying support for consumption growth is income improvement or overspending on savings and credit.Market Impact: The US dollar and US Treasury yields are relatively strong, leading to a divergence in market sentiment.
From a market perspective, this relatively strong core consumption data will provide some upward pressure on the US dollar and US Treasury yields, but the upside potential is uncertain, and whether consumption can be sustained remains to be seen and will depend on credit data. In the equity market, value and high-dividend sectors are relatively more advantageous, while high-valuation growth stocks will be suppressed by high forward discount rates. The bond market environment is cautious in the short term and is not suitable for speculating on a loose monetary policy. (US Dollar Index 1-minute chart, source: FX678)Auxiliary Perspective: A Simple Supplement to the Walsh AI Framework
The three-scenario AI framework proposed by Federal Reserve's Warsh can serve as a supplementary reference. The current resilience of consumption temporarily rules out the possibility of a rapid collapse in demand caused by the decline in AI capital expenditure. However, based solely on retail data, it is not possible to distinguish whether the strong consumption stems from a healthy boom with a general improvement in national income or from a divergent pattern where benefits are concentrated on the capital side and residents rely on overdrafts to maintain consumption. This requires further verification from subsequent data such as wages and credit.- Risk Warning and Disclaimer
- The market involves risk, and trading may not be suitable for all investors. This article is for reference only and does not constitute personal investment advice, nor does it take into account certain users’ specific investment objectives, financial situation, or other needs. Any investment decisions made based on this information are at your own risk.