Without forward guidance, the market will pressure for interest rate hikes at every policy meeting.
2026-10-02 00:34:15
Let's quickly review the Federal Reserve's actions over the past few months. Two weeks before the Fed's policy meeting on July 29, June's core CPI data showed inflation was flat, meaning zero. Warsh's press conference at that time is now considered a major blunder, but objectively speaking, his statement was simply that the oil shock had not spread to a broader level of inflation, and based on the actual data, this assessment was entirely valid. The market did not accept this statement, and market volatility ensued. The yield curve steepened sharply, and commentators questioned the credibility of the Fed's policies under Warsh's leadership. This situation was ultimately resolved by several events: the unexpected announcement from the US Treasury Department on August 19, the hawkish Jackson Hole Economic Symposium on August 28, and the interest rate hike on September 16. All the debate surrounding the Fed's credibility, and the ensuing steepening yield curve, subsided. The price Warsh paid was an interest rate hike. 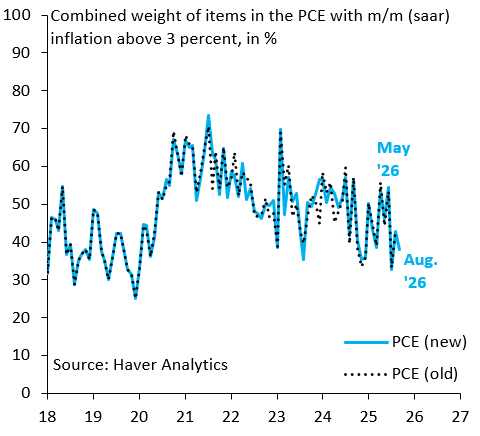 Now, the same scenario seems poised to repeat itself. The chart above shows the weight of items in the Personal Consumption Expenditures (PCE) price index with a monthly annualized inflation rate higher than 3%. This is the very indicator Warsh cited in his Jackson Hole keynote address, and in my view, he mistakenly used it as the basis for shifting to a hawkish stance. Yesterday's PCE data included multiple revisions dating back to 2021; the blue line in the chart is the indicator calculated based on the latest revised data, while the black dotted line represents the result before the data revision. It is clear that the weight of items with inflation higher than 3% is steadily declining, with only a brief rebound in March-May due to the transmission of soaring oil prices to the PCE. Warsh's view in July—that inflation has not spread—was accurate then, and it is even more so now. I have repeatedly emphasized that the current inflation situation does not support interest rate hikes, let alone urgently require one later this month.
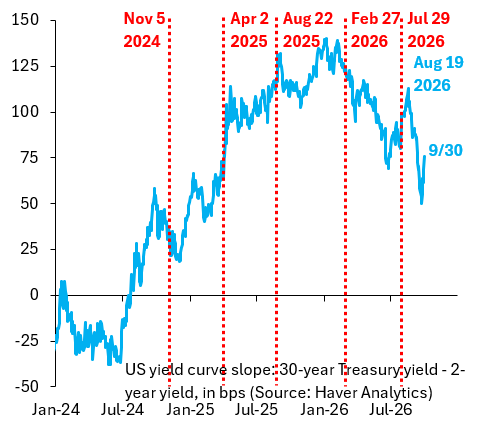 But here's the problem: as the market lowered its bets on a rate hike on October 28 (after the release of the PCE data and New York Fed President Williams' speech on September 29, the probability of a rate hike had fallen from 70% to 40%), the yield curve steepened again. The chart above shows the spread between the 30-year and 2-year Treasury yields. The yield curve is steepening rapidly again, and the market is poised for another round of market volatility. I do agree that forward guidance should be gradually reduced, but the current operating model is no longer effective. Every interest rate decision has become a standoff between the Fed and the market. To fundamentally resolve this situation, the Fed needs to send clearer and more predictable policy signals to the market. This task cannot be left to Williams or other members of the Federal Open Market Committee (FOMC); it must be done by Warsh himself. Unless this is done, every FOMC meeting will become a tug-of-war, with no result until the very last moment, which is not good for any party.
Now, the same scenario seems poised to repeat itself. The chart above shows the weight of items in the Personal Consumption Expenditures (PCE) price index with a monthly annualized inflation rate higher than 3%. This is the very indicator Warsh cited in his Jackson Hole keynote address, and in my view, he mistakenly used it as the basis for shifting to a hawkish stance. Yesterday's PCE data included multiple revisions dating back to 2021; the blue line in the chart is the indicator calculated based on the latest revised data, while the black dotted line represents the result before the data revision. It is clear that the weight of items with inflation higher than 3% is steadily declining, with only a brief rebound in March-May due to the transmission of soaring oil prices to the PCE. Warsh's view in July—that inflation has not spread—was accurate then, and it is even more so now. I have repeatedly emphasized that the current inflation situation does not support interest rate hikes, let alone urgently require one later this month. But here's the problem: as the market lowered its bets on a rate hike on October 28 (after the release of the PCE data and New York Fed President Williams' speech on September 29, the probability of a rate hike had fallen from 70% to 40%), the yield curve steepened again. The chart above shows the spread between the 30-year and 2-year Treasury yields. The yield curve is steepening rapidly again, and the market is poised for another round of market volatility. I do agree that forward guidance should be gradually reduced, but the current operating model is no longer effective. Every interest rate decision has become a standoff between the Fed and the market. To fundamentally resolve this situation, the Fed needs to send clearer and more predictable policy signals to the market. This task cannot be left to Williams or other members of the Federal Open Market Committee (FOMC); it must be done by Warsh himself. Unless this is done, every FOMC meeting will become a tug-of-war, with no result until the very last moment, which is not good for any party.
- Risk Warning and Disclaimer
- The market involves risk, and trading may not be suitable for all investors. This article is for reference only and does not constitute personal investment advice, nor does it take into account certain users’ specific investment objectives, financial situation, or other needs. Any investment decisions made based on this information are at your own risk.