With a $40 trillion debt looming, is the US preparing to use inflation to "default"? Jim Rickards: Gold is the savers' weapon of retaliation.
2026-10-02 11:12:17
With the 10-year US Treasury yield hitting a new high since 2002, a renewed debate has intensified regarding the future of the US debt crisis. Jim Rickards, author of *Currency Wars*, offers a rather direct assessment: Washington will not truly repay its over $40 trillion debt, nor will it solve the problem through serious spending cuts; ultimately, it is more likely to dilute the debt through inflation. For dollar holders, this represents a slow and insidious loss of purchasing power; for gold holders, it could be a form of retaliation. Rickards believes that gold has already pointed savers towards a safe haven. The following analysis examines six aspects: debt logic, historical experience, household pressure, the Russian case, gold strategies, and inflation data, ultimately returning to the same conclusion. 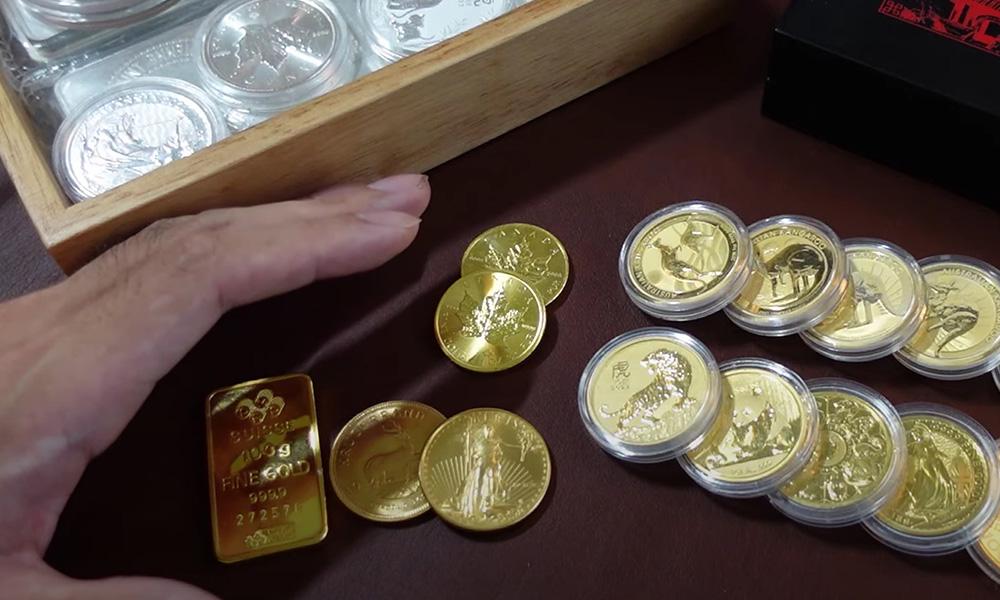
First, debt will not be resolved through repayment, but rather through inflation.
The US government debt has exceeded $40 trillion, with annual interest payments alone reaching approximately $1 trillion. Rickards doesn't believe anyone in Washington truly intends to pay off this debt. He argues that national debt doesn't need to be paid off, nor will it be; what's truly needed is continuous rollover at reasonable interest rates. However, rollover is becoming increasingly difficult. On Thursday, the 10-year US Treasury yield hit 5.34%, its highest level since 2002, accelerating the global bond sell-off. The UK 30-year gilt yield broke 6% for the first time since 1998, and the Bloomberg Government Bond Index just experienced its worst quarter since 2024. For every percentage point increase in yields, the cost of rolling over debt in Washington rises. The Congressional Budget Office has projected net interest costs of approximately $1 trillion this fiscal year. Rickards, a lawyer and author who has advised the US intelligence community on financial threats, believes the real solution is not debt repayment or spending cuts, but inflation. Ultimately, those holding dollars will pay for this inflation. His answer is hard assets, citing Russia's gold reserves as proof of this strategy's effectiveness.II. Lessons from World War II: How Nominal GDP Can Reduce Debt
Rickards shifts the focus back to the post-World War II era. According to data from the St. Louis Federal Reserve, federal debt peaked at approximately 118% of GDP in 1946, but fell to about 31% by 1981. The debt itself never stopped growing; what truly changed was the size of the economy in current dollar terms, and a large portion of that growth came from price increases. Rickards argues that the problem isn't the debt itself, because it tripled; nor is it the deficit, because GDP grew. But when discussing debt, one cannot look solely at real GDP, but rather at nominal GDP. Nominal GDP equals real GDP plus inflation. This is crucial for large borrowers like the U.S. government. Rickards points out that inflation benefits debtors. If you are a debtor, you would like inflation because the nominal amount of dollars you owe remains the same, but their real value decreases. It's like someone telling you, "Here's your trillion dollars; may you be able to afford a loaf of bread." Who is the world's largest debtor? The United States of America. The Federal Reserve, however, states that it is fighting inflation, not welcoming it. It raised interest rates in September for the first time since 2023, with Chairman Kevin Warsh calling inflation “too high…for too long.” But Ricardi’s view is that, on a multi-decade scale, the mathematical logic of debt will ultimately prevail over political promises.Third, depositors have already felt the pressure.
This squeeze is clearly visible in household data. Americans increased their inflation-adjusted spending by 0.6% in August, the largest increase since March 2025. But their inflation-adjusted income didn't grow at all, and the savings rate slipped to 4.1%, the lowest since 2022, according to the Bureau of Economic Analysis. Rickards says inflation doesn't need to be dramatic to cause real damage. He says 3% inflation can halve the value of the dollar in about 24 years. Extend that process over a 48-year career, and three-quarters of purchasing power is gone. If inflation reaches 4% or 5%, the situation is even worse; the dollar is like ice melting in your hand. He says retirees are the worst off because their pay rises always come after prices have already changed. Social Security is adjusted annually, but that's ex-post. Any increase in Social Security payments in 2027 will be based on 2026 inflation. So retirees are always slightly behind the curve. Rickards believes the victims are those without assets, or various fixed-income groups, who cannot adjust.IV. Lessons from Russia's Frozen Reserves for Gold Holders
For Rikaz, the most compelling case for gold came in 2022 when Western governments froze approximately $300 billion of Russia's reserves held overseas. Moscow's gold reserves, held domestically, became the only asset they couldn't access. Rikaz says Russia reaped over $150 billion in market value profits from gold. On one hand, the US couldn't access this gold; on the other hand, gold prices rose due to concerns that the US Treasury might steal Treasury bonds. Russia profited handsomely from gold, so it truly played its role. Data supports his claim. According to Kitco News, as of August 1st, the Central Bank of Russia held approximately 73.2 million ounces of gold. From approximately $1900/ounce at the beginning of 2022 to approximately $4160/ounce currently, the value of these holdings has increased by approximately $165 billion. Gold hit a record high of $5589.38 per ounce on January 28th and traded near $4158 on Thursday. This is still higher than the price of approximately $3866 a year ago. Ricards doesn't expect central banks to drive the next big rally, but he believes they will limit the downside. He says central bank buying won't cause a surge, but it does establish a bottom. He calls it an asymmetric trade; your downside is limited because the central bank is always there buying and setting a floor. However, he cautions that you must make sure you actually own gold. Holding gold futures, unallocated gold contracts, gold options, or ETFs doesn't equate to owning gold; it only means owning a contract.Fifth, inflation data has softened somewhat, but this should not be described as an easing.
Wall Street received some good news this week. Core PCE, the Fed's preferred inflation gauge, rose 0.2% in August, up 3.0% year-over-year, below economists' expectations of 3.3%. According to CME FedWatch, the probability of another rate hike in October fell to 25% on Wednesday from 70.9% a week earlier. Ricards expects the Fed to hold rates steady at its October 27-28 meeting. December is another matter, though; he believes the Fed might raise rates then. He also disagrees with the notion that inflation has been defeated. Ricards said that if inflation falls from 3.7% to 3.4%, the New York Times will say inflation has fallen, but prices haven't. This only means prices are still rising, just at a slower pace. Prices are still well above pre-2022 levels, when annual inflation peaked at 9.1%, according to the Bureau of Labor Statistics.In conclusion: The real risk is not default, but the gradual erosion of the dollar's purchasing power.
Connecting the dots of Ricards's logic reveals a clear chain: US government debt exceeds $40 trillion, with annual interest payments of approximately $1 trillion. With the 10-year Treasury yield rising to 5.34%, the cost of rolling over the debt will only increase. Truly repaying the debt or drastically cutting spending is extremely difficult both politically and economically; therefore, inflation becomes the most realistic escape route. The cost won't suddenly appear as a "default," but will fall on cash holders, those with fixed incomes, and retirees through a long-term decline in the purchasing power of the dollar. The case of Russia's frozen reserves illustrates that gold has unique value in an environment of sanctions and financial weaponization; and central bank buying may provide a floor for gold prices. Ricards's core judgment is not to predict a particular interest rate hike or cut, but to remind people that debt doesn't disappear, it will only be repriced. Gold may not bring sudden wealth, but in an era where Washington may use inflation to resolve debt, it's more like a way for savers to fight back against currency devaluation. At 11:09 Beijing time, spot gold is currently trading at $4168.17 per ounce.- Risk Warning and Disclaimer
- The market involves risk, and trading may not be suitable for all investors. This article is for reference only and does not constitute personal investment advice, nor does it take into account certain users’ specific investment objectives, financial situation, or other needs. Any investment decisions made based on this information are at your own risk.