With the probability of a Fed rate hike falling from 70% to 20%, is there any hope for gold bulls?
2026-10-05 21:44:17
Gold prices continued their sideways trend during the New York session on Monday (October 5), trading around $4,155 per ounce, up 0.30% on the day. Gold is currently caught between cooling bets on a Fed rate hike and a stronger dollar, while US Treasury yields remain near multi-year highs. 
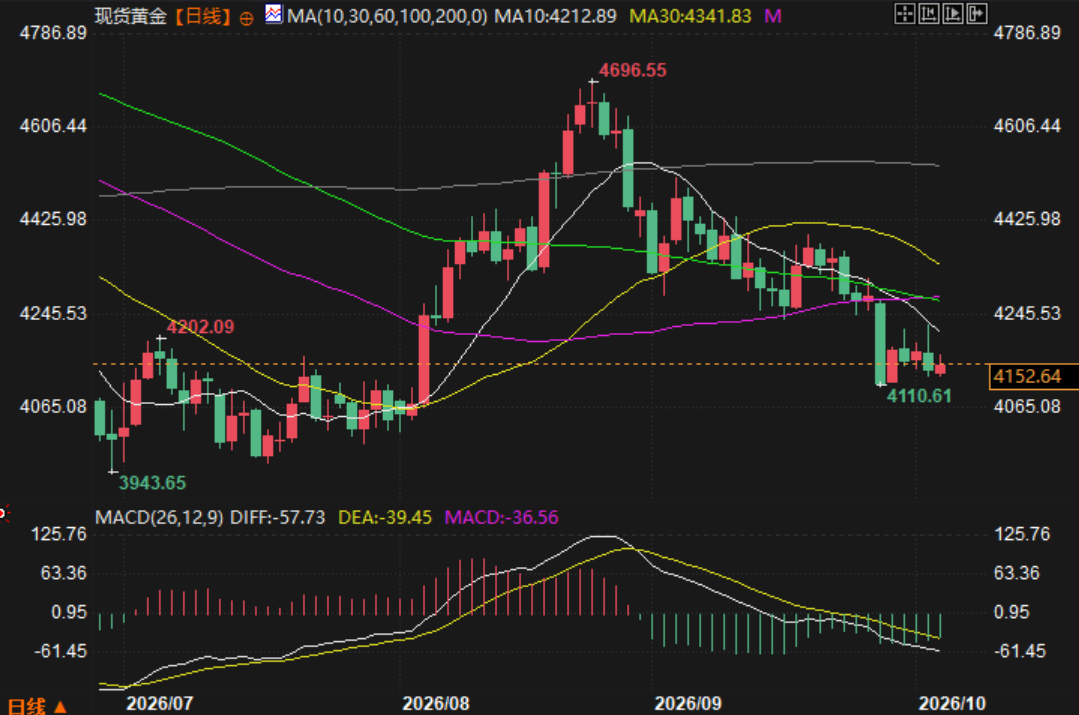 (Spot gold daily chart, source: EasyTrade) At 21:29 Beijing time, spot gold was trading at $4152.36 per ounce.
Dovish repricing: Probability of an October rate hike drops from 70% to 20%.
Recent US economic data has significantly weakened the basis for a Federal Reserve rate hike in October. Data released last Friday showed that non-farm payrolls increased by only 29,000 in September, far below the expected 90,000; the combined job growth for the first two months was revised down by 60,000; the unemployment rate rose to 4.2%; and annual wage growth slowed to 3.0%. This follows the weaker-than-expected August PCE inflation report and its downward revision. According to the CME FedWatch Tool, traders are currently pricing in only about a 20% probability of an October rate hike, down from nearly 70% last week. This dovish repricing has provided some support for gold, as gold does not generate interest, and the cooling of rate hike expectations reduces the opportunity cost of holding gold.Policy outlook remains tight: Inflation concerns and energy risks limit gold price gains.
However, the broader policy outlook remains tilted towards further tightening. Policymakers remain concerned about inflation exceeding the 2% target, while Middle East tensions persist the risk of energy-driven inflation. This limits upside potential for gold while supporting the dollar and Treasury yields. Economists at Deutsche Bank believe that despite disappointing overall non-farm payroll data, the broader labor market picture remains relatively resilient, especially when combined with recent ADP and initial jobless claims data. Based on this, the bank continues to expect two more 25-basis-point rate hikes from the Fed in the coming quarters. The bank added that since the September meeting, the Fed's communication has generally reinforced the pace of quarterly rate hikes implied in the September summary of economic projections; therefore, despite the weak non-farm payroll data, its view on the Fed's path remains largely unchanged.The dollar strengthened as political and fiscal concerns in France weighed on the euro, pushing the dollar index to its highest level since April 2025.
The dollar was also supported by a sharp decline in the euro due to heightened political and fiscal concerns in France. The dollar index traded around 102.25, having touched 102.53 earlier in the session, its highest level since April 2025. Meanwhile, the benchmark 10-year US Treasury yield remained around 5.30%, having reached 5.34% last week, its highest level since 2002. A stronger dollar makes gold more expensive for overseas buyers, while higher yields increase the opportunity cost of holding gold, which does not generate interest.Market focus for the future: ISM Services PMI, FOMC minutes, and subsequent non-farm payroll data.
Looking ahead, the US economic calendar includes the ISM Services PMI released on Monday, the September FOMC meeting minutes on Wednesday, initial jobless claims on Thursday, and the preliminary University of Michigan Consumer Sentiment Index and inflation expectations on Friday. These data will provide new directional guidance for gold. The FOMC meeting minutes will be particularly closely watched, as they will reveal the committee's commitment to its guidance of one more rate hike this year. A dovish tone could confirm the market's dovish repricing, providing support for gold; a hawkish tone could reignite expectations of further rate hikes, putting downward pressure on gold prices.Summarize
Gold is currently in a tug-of-war between bulls and bears. The dovish repricing by the Federal Reserve—with the probability of an October rate hike decreasing from 70% to 20%—has provided some support for gold prices, as the cooling of rate hike expectations reduces the opportunity cost of holding gold. However, a stronger dollar, the 10-year Treasury yield remaining around 5.30%, and a broader policy outlook still leaning towards tightening are collectively limiting gold's upside potential. Deutsche Bank believes the labor market outlook remains resilient and continues to expect two more rate hikes in the coming quarters. French political and fiscal concerns have weighed on the euro, pushing the dollar index to its highest level since April 2025. Amid this tug-of-war between dovish repricing and a strong dollar, gold is likely to remain range-bound in the short term, with the FOMC minutes and the ISM Services PMI being key catalysts for short-term direction. (Spot gold daily chart, source: EasyTrade) At 21:29 Beijing time, spot gold was trading at $4152.36 per ounce.
- Risk Warning and Disclaimer
- The market involves risk, and trading may not be suitable for all investors. This article is for reference only and does not constitute personal investment advice, nor does it take into account certain users’ specific investment objectives, financial situation, or other needs. Any investment decisions made based on this information are at your own risk.