2026 US Midterm Elections: Democratic Control of Congress, Investor Q&A
2026-11-04 18:16:25
The current AI trading frenzy is at a delicate juncture, with the market witnessing a political reshuffling. The Democrats, who were initially poised to regain control of the House of Representatives, have seen their strong performance in the Senate race turn what the Republicans initially anticipated as a midterm election loss into a Democratic victory in both houses. This means that Trump will face even fiercer congressional confrontations in his remaining two years in office. Following this news, US stock index futures fell, with the technology sector under significant pressure; US Treasuries, gold, and non-US currencies received support.  However, investors need to distinguish three things: the short-term market reaction to the unexpected election results, the policies that can be implemented and adjusted in reality, and the fundamentals of the companies themselves.
 Question 8: Will the US dollar enter a sustained downward trend? The logic of a weakening dollar holds true, but it's too early to conclude that "the era of America's relative advantage is over." The direct transmission chain is clear: cooling expectations of increased fiscal spending lower US Treasury yields, thus weakening the dollar's interest rate advantage. Simultaneously, increased uncertainty surrounding the prospects of leading US tech stocks will prompt some overseas portfolios to diversify their allocations. The euro and yen have already reacted to this. However, the dollar's ultimate trajectory depends on the relative economic growth rate and interest rate differential. If the US economy continues to outperform other economies, or if geopolitical conflicts escalate, dollar buying will return. Our view: It's more appropriate to reduce excessive concentration of dollar assets in portfolios rather than aggressively shorting the dollar. Question 9: What does this mean for US Treasuries? Are long-duration bonds becoming attractive again? This election has increased the tactical allocation value of US Treasuries. Democratic Congress's constraints on a new round of fiscal stimulus have led investors to reassess growth paths, financing needs, and interest rate trends. Two factors are favorable for bonds: downward revisions in growth expectations and a decline in the fiscal expansion premium previously priced into yields. However, a policy deadlock does not equate to a debt reduction plan. Regardless of which party controls Congress, the US remains burdened with high interest payments and structural fiscal pressures. We prefer medium-duration, high-quality bonds rather than betting on ultra-long-term bonds. If the economy slows, the mid-section of the US Treasury yield curve can balance coupon yields and price appreciation potential. Key risk: Even with a weakening economy, a rebound in inflation or an increase in the term premium will still push up long-term yields. Question 10: Is gold the winner in this midterm election? Multiple factors support gold: declining US Treasury yields, a weaker dollar, and renewed political uncertainty. Gold's allocation value comes not only from the election. Geopolitical tensions, concerns about fiscal sustainability, and the need for diversification due to over-concentration in equity holdings continue to support the strategic allocation logic of gold. However, investors should distinguish that gold is a portfolio hedging tool, not a short-term speculative target for betting on election-related market movements. Once US Treasury yields rebound and the dollar recovers, gold prices will likely correct again. Escalating geopolitical conflicts are a significant variable, especially the intensification of tensions between the US and Iran, which will disrupt gold prices. Our view: Gold is suitable as a base position to hedge against inflation, geopolitical shocks, and policy uncertainties, but not for short-term speculation based on election news.
However, investors need to distinguish three things: the short-term market reaction to the unexpected election results, the policies that can be implemented and adjusted in reality, and the fundamentals of the companies themselves.Part One: The Reset of the Political Landscape
Question 1: What does Democratic control of both the House and Senate mean for the US economy and markets? The most important impact is a shift in Washington's policy tone from relative unity to significant political gridlock. Trump remains president, but a Democratic-controlled Congress will severely restrict his ability to advance legislation on taxes, fiscal stimulus, and government spending. However, the Democrats cannot rewrite policies at will, as the president holds veto power. A more likely scenario is increased political confrontation, stronger congressional oversight, and legislative deadlock over the next two years, rather than the immediate overturning of existing policies. At the market level: the certainty of future fiscal stimulus decreases, and regulatory uncertainty increases. Short-term market reactions are mainly driven by three concerns: narrowing room for further fiscal support, stronger regulatory scrutiny of AI and large technology companies, and a potential slowdown in the growth momentum supporting the relatively strong US stock market. Question 2: Does this signify the end of Trump's economic agenda? Not the end, but rather a constraint; it will not be completely dismantled. It is crucial that Congress and the White House belong to different branches of power and possess different policy tools. Taxation and Fiscal Stimulus: New tax cuts and large-scale spending bills will be more difficult to pass; existing tax laws will not automatically become invalid. AI and Technology: Congress can strengthen oversight and limit new incentive policies, but comprehensive regulatory bills still face presidential veto obstacles. Trade and Tariffs: Trump retains a large amount of executive power (subject to legal constraints); merely changing Congress does not eliminate tariff risks. Energy and Geopolitics: The White House retains significant influence over foreign policy, sanctions, and military arrangements. Personnel Nominations: With the Democrats controlling the Senate, the confirmation process for judges and senior officials will become significantly more difficult. Potential Risks: Continued political polarization could trigger budget disputes, government shutdowns, or sharp market volatility due to the debt ceiling. Our View: The market may be overreacting, simply equating a Democratic-led Congress with a weakening economy. The current policy framework will largely remain intact, and the private sector investment cycle will continue. Question 3: Will a Democratic victory lead to a decline in inflation and interest rates? This may alleviate upward pressure on US Treasury yields, but the inflation logic itself is more complex. The probability of further stimulus through deficit financing has decreased. Compared to previous policy expectations, the market will likely lower its expectations for the scale of US Treasury issuance and long-term financing needs. This is also why US Treasury yields fell after the election results were released. However, a cooling of fiscal stimulus does not automatically mean lower inflation. Tariffs, energy prices, wage levels, and supply bottlenecks can still push up prices. For the Federal Reserve, the election results will not change its policy objectives. If the economy slows down but inflation remains high, monetary policy choices will become more complex. Investment implications: Cooling growth expectations are beneficial to bonds, but a sustained bull market in bonds requires verification from economic data and inflation trends, and cannot rely solely on election news.Part Two: The AI Sector Undergoes Revaluation
Question 4: Why did tech and AI stocks experience particularly sharp declines? The election accelerated a revaluation of the AI market that had already begun. Leading up to the midterm elections, AI sector valuations were high, and capital expenditure commitments were massive, leading to growing investor concerns about the speed at which AI investment would translate into profits. Now, a Democratic Congress adds another layer of regulatory uncertainty. There are three main risks: 1. Increased oversight: Congress will launch investigations into AI companies, market competition, consumer protection, data privacy, and model security. 2. Data center restrictions: Electricity load, grid costs, water consumption, and project approvals will face stricter scrutiny; local resistance will drive up project costs and lengthen construction periods. 3. Uncertainty regarding capital expenditure: With a tighter regulatory environment, investors will place higher demands on the funding sources and profitability of AI infrastructure projects. Congressional scrutiny may force the implementation of AI safety standards, the formation of independent model evaluation mechanisms, and greater responsibility on data center builders. However, this does not equate to a purely anti-AI policy approach. AI is crucial to US competitiveness, especially compared to China, and both parties intend to maintain the US's leading position in this field. Our view: The election results are merely a catalyst for repricing. A deeper contradiction lies in this: if a credible path to returns is not visible, investors are no longer willing to simply pay for AI capital expenditures. Question 5: Is this the beginning of the end of the AI boom? No. But it marks a new phase in the AI market, shifting from an investment expansion frenzy to a profit realization cycle. Previously, companies could gain a premium in stock price simply by expanding their AI computing power. Now, investors are asking more stringent questions: Where will the expansion funds come from? How large will the debt scale be? How long will it take for computing power to generate revenue? Who will ultimately reap the economic benefits? The AI sector is gradually differentiating into three types of targets: Mature leaders: Profit platforms, core chip manufacturers, and storage companies with stable balance sheets and strong demand certainty. They are more resilient, but their valuations still have room for compression. Heavy asset infrastructure providers: Data center developers and highly leveraged computing power providers, facing multiple risks related to financing, electricity, and regulation. AI application providers: Using AI to improve production efficiency, profit margins, and customer experience without having to bear the full cost of infrastructure investment themselves. In the next stage of the AI market, funds may favor the third type while selectively investing in the first type. This also means that high-quality AI investment opportunities are not necessarily limited to the traditional semiconductor and cloud vendor sectors. Question 6: Is it a good time to buy US tech stocks now? Selective investment is possible, but you shouldn't buy the entire sector just because stock prices have fallen. Nasdaq 100 futures are approaching technical oversold territory, and the 14-day Relative Strength Index (RSI) is nearing 30. Given the crowded open interest, this could trigger a short-term rebound. However, futures prices have also fallen below the 200-day moving average, indicating technical selling pressure and new short positions, which could amplify volatility. It's important to distinguish between short-term technical rebounds and fundamental trend reshaping. For long-term investors, we prefer AI leaders with stable profits, healthy balance sheets, a solid customer base, and sustainable cash flow. Be cautious about highly leveraged infrastructure companies—these business models heavily rely on continuous capital expenditure and a relaxed financing environment. Also, don't assume that a decline in US Treasury yields will save all growth stocks. A lower discount rate is beneficial for valuations, but if earnings expectations are revised downwards simultaneously, the benefit will be offset. In summary: selectively invest in high-quality stocks in batches; don't gamble on perfectly timed bottom-fishing. Nvidia's upcoming financial reports and other profit data will be a better test of the logic behind AI investment than the election itself.Part Three: Asset Allocation Strategies
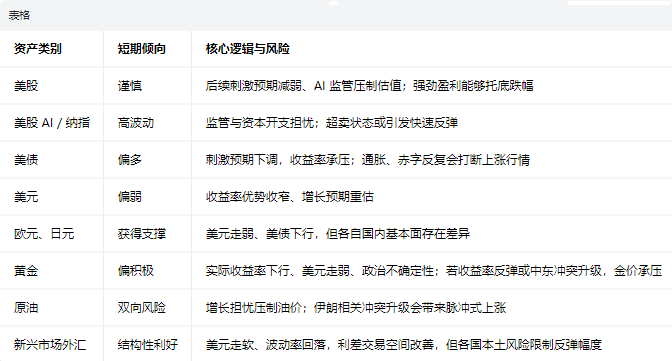
Question 7: What are the prospects for stocks, bonds, foreign exchange, and commodities after the Democrats control Congress? The following is a directional assessment, not a real-time price forecast; short-term refers to the next few days to weeks. (Table) Question 8: Will the US dollar enter a sustained downward trend? The logic of a weakening dollar holds true, but it's too early to conclude that "the era of America's relative advantage is over." The direct transmission chain is clear: cooling expectations of increased fiscal spending lower US Treasury yields, thus weakening the dollar's interest rate advantage. Simultaneously, increased uncertainty surrounding the prospects of leading US tech stocks will prompt some overseas portfolios to diversify their allocations. The euro and yen have already reacted to this. However, the dollar's ultimate trajectory depends on the relative economic growth rate and interest rate differential. If the US economy continues to outperform other economies, or if geopolitical conflicts escalate, dollar buying will return. Our view: It's more appropriate to reduce excessive concentration of dollar assets in portfolios rather than aggressively shorting the dollar. Question 9: What does this mean for US Treasuries? Are long-duration bonds becoming attractive again? This election has increased the tactical allocation value of US Treasuries. Democratic Congress's constraints on a new round of fiscal stimulus have led investors to reassess growth paths, financing needs, and interest rate trends. Two factors are favorable for bonds: downward revisions in growth expectations and a decline in the fiscal expansion premium previously priced into yields. However, a policy deadlock does not equate to a debt reduction plan. Regardless of which party controls Congress, the US remains burdened with high interest payments and structural fiscal pressures. We prefer medium-duration, high-quality bonds rather than betting on ultra-long-term bonds. If the economy slows, the mid-section of the US Treasury yield curve can balance coupon yields and price appreciation potential. Key risk: Even with a weakening economy, a rebound in inflation or an increase in the term premium will still push up long-term yields. Question 10: Is gold the winner in this midterm election? Multiple factors support gold: declining US Treasury yields, a weaker dollar, and renewed political uncertainty. Gold's allocation value comes not only from the election. Geopolitical tensions, concerns about fiscal sustainability, and the need for diversification due to over-concentration in equity holdings continue to support the strategic allocation logic of gold. However, investors should distinguish that gold is a portfolio hedging tool, not a short-term speculative target for betting on election-related market movements. Once US Treasury yields rebound and the dollar recovers, gold prices will likely correct again. Escalating geopolitical conflicts are a significant variable, especially the intensification of tensions between the US and Iran, which will disrupt gold prices. Our view: Gold is suitable as a base position to hedge against inflation, geopolitical shocks, and policy uncertainties, but not for short-term speculation based on election news.Part Four: What should investors do now?
Question 11: Should we reduce our holdings of US stocks and shift to overseas markets? The reasons for diversification are strengthening, but this doesn't mean abandoning US stocks. US companies still have significant advantages in technological leadership, profitability, innovation, and financing channels, and the political deadlock won't erase these advantages. However, with market funds heavily concentrated in US tech stocks, investors will re-evaluate whether these companies can continue to outperform under high valuations. Three diversification directions worth considering: 1. Asian markets: Select Chinese technology and related companies that benefit from domestic AI applications. 2. Broad-based US stocks: Equal-weighted indices, high-quality stocks outside of giant tech giants, the healthcare sector, and companies that improve profit margins through AI. 3. Multi-asset portfolio: Medium-duration bonds + gold as supplements; don't let portfolio returns rely entirely on stocks. Key reminder: A pullback in US tech stocks doesn't necessarily mean all overseas stocks will rise. If the market enters a full-blown risk-averse mode, global equities will be under pressure. Question 12: What factors will reverse the current bearish market sentiment? Three core catalysts: First, the realization of AI profits. Leading tech companies have proven that capital expenditure can translate into revenue and profit, and market panic regarding the AI cycle will subside. Second, economic data. Strong US employment and growth data will overturn the expectation that "political gridlock significantly drags down the economy"; sticky inflation will also end the rise in US Treasury bonds. Third, clear policy expectations. If investors judge that the new Congress will only create noise and will not substantially impact AI investment, the regulatory risk premium will fall. Negative scenario risks: political uncertainty coupled with weakening corporate profits, tightening AI financing conditions, or sudden geopolitical shocks. Question 13: What should we focus on most before the end of the year? Compared to chasing election news, focus on four areas: 1. Is AI capital expenditure truly slowing down, or is the market simply demanding higher returns? Pay attention to Nvidia's earnings report, cloud vendor capital expenditure guidance, data center financing, and semiconductor orders. 2. Is the decline in US Treasury yields driven by improved inflation expectations or deteriorating growth expectations? The two have completely different implications for the stock and credit markets. 3. Can the weakening of the US dollar continue? Continued weakening will continue to benefit Asian stock markets, emerging market currencies, and gold. 4. Will the policy deadlock escalate into a fiscal confrontation? Budget negotiations, debt ceiling progress, congressional hearings and investigations, and newly enacted data center regulations in various states could all become new sources of volatility. The next two months will provide the answer: will this midterm election merely accelerate the already initiated sector rotation, or will it mark a fundamental shift in the market's main theme?- Risk Warning and Disclaimer
- The market involves risk, and trading may not be suitable for all investors. This article is for reference only and does not constitute personal investment advice, nor does it take into account certain users’ specific investment objectives, financial situation, or other needs. Any investment decisions made based on this information are at your own risk.