












Sydney:12/24 22:26:56

Tokyo:12/24 22:26:56

Hong Kong:12/24 22:26:56

Singapore:12/24 22:26:56

Dubai:12/24 22:26:56

London:12/24 22:26:56

New York:12/24 22:26:56

2026-09-15 Tuesday

2026-09-22

21:55:49

[Asian Fuel Oil Retraces Gains, Diesel and Jet Fuel Trading Heats Up] ⑴ The Asian high-sulfur fuel oil market retraced some of its gains on Tuesday, after an earlier surge pushed premiums up sharply. ⑵ The premium for 380-cst high-sulfur fuel oil spot over Singapore quotes fell from the previous day, but remained above $50 per tonne. ⑶ The ultra-low sulfur fuel oil spot spread widened to above $37 per tonne, with buyers offering higher prices than the previous trading day. ⑷ Fuel oil crack spreads rose, with the ultra-low sulfur fuel oil crack spread reaching a premium of approximately $22.8 per barrel at the Asian close, and the 380-cst high-sulfur fuel oil crack spread reaching nearly $1.5 per barrel. ⑸ No high-sulfur or ultra-low sulfur fuel oil deals were reportedly concluded in the Singapore trading window. ⑹ Trading in the diesel market became more active, with refineries increasing sales of October cargoes. As inter-month spreads strengthened further, negotiated premiums also increased. (7) The East-West diesel price spread remained at a discount of over $130 per ton. (8) The diesel crack spread fell for the second consecutive trading day, dropping to around $81 per barrel, but remained above the August average. (9) The diesel spot price spread further widened slightly to around $5.8 per barrel, following the strengthening structure of the paper market, although spot trading activity weakened. (10) In the jet fuel market, spot market activity increased, with both buyers and sellers seeking to buy or sell October cargoes. (11) The jet fuel-diesel discount widened further to nearly $4 per barrel, with no jet fuel or diesel deals reportedly concluded in the trading window. (12) Naphtha prices held firm, near the highs reached in July, following the rise in crude oil prices. Escalating geopolitical tensions in the Gulf region pushed premiums sharply higher, with market participants estimating October second-half cargo prices at around $978 per ton, widening the backwardation to around $28 per ton.

21:52:09

[Cotton Hits One-Month Low as Weak Spinning Demand and Harvest Pressure] ⑴ Intercontinental Exchange (ICE) cotton futures fell on Tuesday, hitting a one-month low, pressured by weak spinning demand and harvest pressure. ⑵ The most actively traded December contract fell about 0.7% to around 83.9 cents per pound. ⑶ The contract fell as low as 83.68 cents per pound during the session, its lowest since August 14. ⑷ Brokers said that as the market entered the 80-cent range, spinning mills withdrew their buying, and the market is looking for demand. ⑸ Spinning mill purchases are a key source of cotton demand, and weakened buying interest will cause the market to seek price levels that can attract buyers back, thus putting downward pressure on prices. ⑹ The broker also said that this is currently the time when various crops typically begin to look for harvest lows, and the harvest itself can put pressure on prices. ⑺ Harvest pressure will drag down cotton prices as new supplies enter the market, increasing availability. (8) Meanwhile, corn and soybeans weakened as investors assessed U.S. harvest progress and an unexpected improvement in corn crop ratings. (9) The U.S. dollar strengthened slightly, making U.S. supplies more expensive for overseas buyers, thus pressuring cotton prices. (10) Oil prices remained near a four-month high above $105 a barrel amid renewed attacks by Yemen's Houthi rebels on Saudi Arabia and postponements of Gulf talks with Iran. (11) Rising oil prices increase the manufacturing costs of polyester, a cotton substitute.

21:45:02

[US 6-Week Treasury Bill Auction Imminent; Forward Pricing and Interest Rate Hike Expectations Support Demand] ⑴ The US Treasury will auction approximately $75 billion in 6-week Treasury bills, maturing on October 29, 2026. ⑵ Non-competitive bidding will begin at 11:00 AM Eastern Time, and competitive bidding will begin at 11:30 AM Eastern Time. ⑶ The current pre-issuance level of 6-week Treasury bills is approximately 3.87%, corresponding to a money market yield of approximately 3.89%. ⑷ The bid price for existing 6-week Treasury bills corresponds to a money market yield of approximately 3.84%, with a forward rollover of approximately 5.3 basis points. ⑸ The spread between 1-month and 2-month yields is approximately 9 basis points, equivalent to approximately 2.25 basis points per week; therefore, the 5.3 basis point forward rollover has some value. ⑹ Given the forward rollover valuation, the bidding is expected to be quite active. (7) Following tomorrow's Fed statement, the next meeting is on October 28th, and the pre-issued bonds expire the following day, giving buyers an option to potentially reinvest in a funding environment 25 basis points higher. (8) For direct long positions, it is recommended to bid on the ask side and welcome any opportunities for concessions. (9) The average bid-to-cover ratio for the last six 6-week Treasury bill auctions was 2.89, with indirect bids accounting for approximately 63%, direct bids for approximately 3%, and dealer bids for approximately 30%. (10) Overall, the forward rolling value and the reinvestment options arising from the approaching Fed policy meeting may jointly support demand for this Treasury bill auction.

21:40:40

[US Treasuries Supported by Supply and Interest Rate Hike Expectations] ⑴ US Treasuries rebounded after a brief pullback, but primary market supply and institutional selling limited gains, while potential buying remained. ⑵ During the Tokyo session, US Treasuries faced continued selling pressure due to the spillover effect of Japanese government bonds, with the 20-year Japanese bond auction, concerns about Japanese government spending, and cabinet changes all contributing to the pressure. ⑶ The 10-year US Treasury yield rose above 5%, attracting Asian buyers, but gains during the London session were offset by selling of European bonds and UK government bonds. ⑷ European bonds and UK government bonds were pressured by the absorption of supply from the auction of German 2-year and UK 15-year government bonds, with yields rising to approximately 17-year highs. ⑸ The rebound in US Treasuries from its lows was met with resistance before the futures market opened, with trend-following funds and hedge funds taking the opportunity to sell. ⑹ Buying returned after a sharp decline in New York manufacturing survey data. (7) Traders and short-term funds took advantage of the highs to establish short positions in today's approximately $13 billion 20-year Treasury bond re-issuance, and new investment-grade bond trading also triggered interest rate-locked-in selling. (8) Potential short-covering buying remains, which in turn limits a significant price decline; traders say actual funds are still buying at the 5% level for 10-year Treasury bonds. (9) Speculative and short-term funds are slightly defensive, but still hold short-covering positions, betting that the Fed will raise interest rates by 25 basis points at tomorrow's meeting. (10) The market expects a rate hike to bring a easing rebound, as it suggests the Fed is in anti-inflation mode. (11) Current federal funds futures indicate a 91% probability of a 25 basis point rate hike at Wednesday's meeting, and approximately 95% and 99% probabilities of further 25 basis point rate hikes in October and December, respectively. 12. Overall, US Treasuries are currently under pressure from supply and interest rate hike expectations, but bargain hunting and short covering provide support at the bottom. Going forward, attention will be focused on the Fed's decision and the subsequent path of interest rate hikes.

21:35:31

[Pakistan's Sugar Exports Raise Food Security Concerns] ⑴ Pakistan's decision to allow the export of approximately 108,000 tons of sugar has drawn criticism. ⑵ Reports suggest the decision could drive up domestic prices while benefiting influential sugar mill owners. ⑶ This move reverses the government's previous practice, with reports indicating that Pakistan has imported sugar in recent years to stabilize domestic supply and prices, but now allows the export of existing stocks amid concerns about future shortages. ⑷ This policy could reduce domestic buffer stocks, potentially pushing up sugar prices if local market supply tightens. ⑸ In the past, similar policies often required further imports to address supply shortages. ⑹ In addition to consumer concerns, environmental concerns have also been raised, with reports stating that sugarcane is an extremely water-intensive crop, consuming large amounts of dwindling groundwater reserves. ⑺ Reports argue that by subsidizing sugar mills through state-supported safeguards and artificial export incentives, the government is effectively exporting scarce water resources to international buyers at a discount. ⑻ Furthermore, policies encouraging sugar production and exports could divert land and resources away from other crops, including wheat. (9) The report also stated that political influence within Pakistan's sugar industry facilitated policy decisions favorable to sugar mill owners. (10) The report mentioned that the Competition Commission of Pakistan had issued warnings regarding the accuracy of data used by the industry for export decisions. (11) Previous reform proposals advocated reducing government intervention in the sugar trade, allowing market forces to determine production, pricing, and imports. (12) However, the report indicated that reducing available inventory could make consumers more vulnerable to future prices.

21:34:34

[Fed Rate Decision Preview: Opinions Divided] ⑴ The market expects the Federal Open Market Committee to raise the target for the federal funds rate by 25 basis points this week, but some experts believe that a rise to the 3.75% to 4% range is not a certainty. ⑵ One strategist pointed out that stronger-than-expected core services inflation has exacerbated concerns about the potential spread of price pressures, reinforcing the rationale for a recent policy response, but he does not expect aggressive tightening. ⑶ This strategist stated that short-term Treasury yields have already signaled the need for policy to move upward, but the spread between the 2-year yield and the federal funds rate shows that the Fed is not significantly lagging behind the curve; the benefit of a weaker bond market is that short-term yields have already reflected expectations of further tightening, so even if the Fed acts, there is no need for a significant further increase. ⑷ He also believes that tightening may support long-term bonds, as this strengthens the credibility of the Fed's efforts to combat inflation. ⑸ One chief global strategist stated that the focus of the debate is no longer whether to act this week, but how many rate hikes this round will occur, and he expects the Fed will not end the cycle in one go. (6) This strategist believes that the midterm elections mean that October may see no change in interest rates, with December being the most likely window for subsequent rate hikes. As long as growth and earnings remain strong, risk assets can absorb two to three rate hikes, but if inflation becomes more stubborn, forcing the Fed to extend its tightening cycle, the outlook will be significantly more challenging. (7) An institutional investment strategy head believes that inflation data reinforces the basis for recent rate hikes, but will not be a major driver for risk assets. (8) A co-head of fixed income strategy stated that the Fed may need to tighten several times to truly curb inflation, and the longer the Fed waits, the more the bond market will push up yields to complete the tightening for it. (9) This person stated that Treasury yields should remain high until investors are confident that inflation is sustainably falling towards its target, and the path of the 10-year Treasury yield moving towards 5% remains valid. (10) A chief global strategist believes that credibility is another reason for rate hikes. In the absence of forward guidance, market consensus has converged on a rate hike this week; without action, the Chairman and the Committee will severely lose credibility. (11) It is expected that as growth and inflation cool in 2027, the Federal Reserve may hold rates steady in October, and raise rates once more or not at all in December, which should limit further increases in long-term yields. (12) Some chief economists predict that the dot plot will show the committee's increased determination to continue raising rates, and this may continue next year; others believe that if the credibility of rate hikes is restored, short-term yields will rise while long-term yields will stabilize. If the 10-year yield breaks through 5%, it indicates that the market believes one or two actions are not enough.

21:33:43

[Foreign Exchange Options: Market Prepares but Direction Uncertain] ⑴ Ahead of the Federal Reserve, the Bank of Japan, and the Bank of England's decisions this week, the spot and options markets for foreign exchange clearly lack a clear direction. ⑵ Volatility risk premiums have been clearly priced in for this period of concentrated central bank events, but directional bets are surprisingly few, with the euro/dollar pair being a typical example, and the same is true for G10 currencies. ⑶ Despite the spot rate falling towards its August lows, euro/dollar options have seen limited volatility. Implied volatility has hovered near long-term lows for months, with the recent decline only causing a slight increase. Low actual volatility continues to put pressure on the premium. ⑷ The 1-week implied volatility is 5.7, which seems expensive compared to Monday's actual volatility of 1.85, but the indicator rebounded to 3.15 on Tuesday, suggesting that the Federal Reserve may bring short-term volatility to the currency pair. (5) Risk reversal indicators also show restraint, with the 1-month benchmark only showing a 0.15-fold increase in euro put options compared to call options, lower than 0.45 in early September and 0.9 at the end of July, acknowledging the spot decline but not supporting a deeper drop. (6) Fund flows also confirm this, with euro bearish demand not extending significantly below 1.1400. If trading desks truly anticipated a larger decline, positions should be more substantial. (7) Spot hedging related to expiring options may still influence short-term trends. On Tuesday at 10:00 AM New York time, approximately €3.2 billion in options with a strike price of 1.1550 will expire, and on Wednesday, before the Fed's decision, approximately €2.2 billion in options with strike prices between 1.1585 and 1.1600 will expire. (8) A larger accumulation occurred around 1.1500 to 1.1600 on Thursday and Friday. If 1.1500 is breached, approximately €8 billion is concentrated around 1.1400, which could act as a magnet or support level, depending on how the spot market approaches it. (9) USD/JPY options signals are relatively clear. New barrier options have emerged around 150, the downside risk premium has been reduced, and demand is expanding towards strike prices above 155, with some targeting 160.00. (10) This aligns with profit-taking rather than new confidence building on the downside, but it also indicates that traders have not ruled out a return to 160, a view further reinforced by the continued pressure on the yen from soaring oil prices. (11) The risk that trading desks are more concerned about is that the Bank of Japan's hawkish stance on Friday may be less hawkish than expected. (12) Overall, actual volatility remains behind implied levels across regions, indicating that options are pricing in the risks of this week's events, but no one is willing to bet on a continued rise in volatility or a directional breakout.

21:33:34

[ICE Canadian Canola: Trading Volume and Open Interest Changes] ⑴ Data released by Dow Jones Newswires on ICE Canadian Grain Futures trading volume and open interest reflects the previous trading day. ⑵ The November contract traded approximately 28,900 lots, with open interest at approximately 209,500 lots, a decrease of approximately 600 lots from the previous day. ⑶ The January contract traded approximately 17,200 lots, with open interest at approximately 77,000 lots, an increase of approximately 600 lots. ⑷ The March contract traded approximately 8,600 lots, with open interest at approximately 44,500 lots, an increase of approximately 2,100 lots, representing the largest increase in open interest among all contracts. ⑸ The May contract traded approximately 2,200 lots, with open interest at approximately 14,200 lots, an increase of approximately 700 lots. ⑹ The July contract traded approximately 700 lots, with open interest at approximately 9,700 lots, a slight increase of approximately 30 lots. (7) The November 27 contract saw approximately 80 lots traded, with open interest at approximately 6,500 lots, an increase of about 40 lots. (8) Trading volume and open interest for other longer-term contracts remained unchanged. (9) Total trading volume was approximately 57,700 lots, with total open interest at approximately 361,500 lots, an increase of about 2,900 lots from the previous day. (10) Structurally, near-month open interest declined slightly while open interest for longer-term contracts, particularly the March contract, increased significantly, indicating that some funds are shifting to longer-term positions, reflecting some divergence in market expectations regarding future supply and demand.

21:30:12

[Strait of Hormuz, Ship Hit by Unidentified Projectile] ⑴ The UK Maritime Trade Operations Office (MTO) stated that a ship was hit by an unidentified projectile while transiting the Strait of Hormuz. ⑵ The incident occurred around 4:40 AM Beijing time on Monday. No damage or environmental impact was reported. ⑶ The MTO did not immediately disclose the ship's identity, flag state, or type of projectile, nor did it identify the responsible party. An investigation is ongoing. ⑷ There are no immediate reports of injuries or fatalities. More details may be released as the investigation progresses. ⑸ This incident follows a series of maritime security incidents in and around the Strait of Hormuz. The MTO has previously reported similar incidents of ships being hit by unidentified projectiles and has urged vessels in the area to exercise caution and report suspicious activity. ⑹ Due to escalating regional tensions, shipping volume through the waterway has decreased significantly. Only four merchant ships were reported to have passed through on Monday, compared to an average of approximately 125 per day before the war. (7) The Strait of Hormuz is one of the world's most important maritime energy routes, connecting the Persian Gulf with the Gulf of Oman and the Arabian Sea. Any continued disruption could have a wider impact on global oil and gas supplies. (8) From a market perspective, the sharp drop in shipping volume coupled with the attack will further amplify the risk premium for crude oil and gas supplies. The subsequent investigation findings, determination of responsibility, and whether traffic flow can be restored will require close monitoring.

21:29:34

[US Natural Gas: Production Decline and High Temperatures Push Up Prices] ⑴ US natural gas futures rose slightly to a one-week high on Tuesday, with the near-month contract for October delivery rising about 4 cents, or 1.3%, to around $2.94 per million British thermal units (MMBtu), on track for its highest closing price since September 4. ⑵ Driving factors included declining daily production and forecasts indicating continued warmer-than-usual weather until the end of September, with gas consumption for air conditioning and power generation expected to be higher than usual for at least two weeks. ⑶ Financial data agencies estimate that average natural gas production in the 48 contiguous US states rose to about 113.2 billion cubic feet per day in September, higher than the monthly record high set in August. ⑷ However, on a daily basis, Tuesday's production is expected to fall to a two-month low of about 108.4 billion cubic feet. ⑸ Record production and mild spring weather have kept energy companies' inventories above the five-year average since March, but last week's high temperatures are expected to narrow the inventory surplus from 4.8% to 3.6%. (6) Weather forecasts indicate that the weather will be generally warm until September 30th. Since approximately 40% of U.S. power generation relies on gas-fired power plants, demand for cooling gas will remain high. (7) Some organizations predict that average natural gas demand (including exports) in the 48 contiguous U.S. states will decrease from approximately 108.4 billion cubic feet per day this week to approximately 106.1 billion cubic feet per day next week. (8) Regarding liquefied natural gas (LNG) exports, the average daily volume flowing to the nine largest U.S. export plants in September rose to approximately 18.3 billion cubic feet, higher than August's 17.2 billion cubic feet, but lower than the monthly record of 18.8 billion cubic feet set in April. (9) On a daily basis, LNG feedstock gas is expected to fall to a three-week low of approximately 17.7 billion cubic feet on Tuesday; some energy companies plan to conduct approximately two weeks of annual maintenance on an export plant with a daily capacity of approximately 800 million cubic feet from around September 19th. (10) Globally, European benchmark gas prices are near a 44-month high of $27 per million British thermal units (MMBtu), while Asian benchmark prices are around $25. (11) US gas prices have had a limited impact on the Middle East situation, as the US is self-sufficient in natural gas and liquefied petroleum gas (LPG) exporters are already operating at full capacity, limiting export growth before new plants come online. (12) Overall, short-term prices are supported by declining production and high temperatures, but higher-than-normal inventory levels, maintenance of export facilities, and expectations of a seasonal decline in demand may limit upside potential.

21:05:32

US Redbook Retail Sales Annual Rate for the Week Ending September 7

Previous : 8.30 Forecast : -
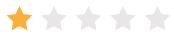
Published Value 8.50

Previous

Real-Time Popular Commodities

Instrument Current Price Change

XAU

4345.82

-32.47

(-0.74%)

XAG

66.047

-0.199

(-0.30%)

CONC

92.09

-3.99

(-4.15%)

OILC

100.12

-3.08

(-2.99%)

USD

100.400

0.190

(0.19%)

EURUSD

1.1467

-0.0018

(-0.16%)

GBPUSD

1.3372

-0.0022

(-0.16%)

USDCNH

6.6923

-0.0023

(-0.03%)
